Buy To Let Mortgages

Thinking About Buying a Property to Let?

Hassle Free
Mortgage Advice

Request A Free Video Call

Whether you are purchasing your first rental property, expanding an existing portfolio or refinancing a property you already own, getting the right mortgage can make a significant difference to your investment.

At Mortgage Links, we provide straightforward buy to let mortgage advice and compare options from a wide range of lenders.

We will explain how lenders assess rental income, deposits, affordability and property type, helping you understand your options before you commit.

Book your free consultation today and speak to an experienced mortgage adviser.
We have access to 90+ Lenders

What We do

How We Can Help Landlords

Buy to let mortgages can be more complex than standard residential mortgages. Different lenders have different rules around rental income, property types, personal income and the number of properties you own.

We can help you:

  • Understand how much you may be able to borrow.
  • Compare buy to let mortgage rates and fees.
  • Check whether the expected rent meets lender requirements.
  • Explore options for first-time landlords.
  • Purchase property personally or through a limited company.
  • Refinance an existing rental property.
  • Raise money from a buy to let property where appropriate.
  • Expand or restructure an existing property portfolio.
  • Understand the mortgage costs before proceeding.
  • Arrange suitable protection where required.
 

We will guide you through the process from your initial enquiry to mortgage offer and completion.
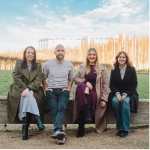
Mortgage Links Team Sheffield
Established

2022

What Can We Help With?

Here to help you through every stage of your mortgage journey

First-time buyer mortgage iconA house, keys and approved mortgage document representing a first-time buyer mortgage.FIRST-TIMEBUYERMORTGAGE
First-Time Landlord Mortgages

Buying your first rental property can feel complicated.

We will explain the deposit required, how rental income is assessed and which lenders may consider first-time landlords.

Agreement in Principle mortgage iconA clipboard marked AIP Agreement in Principle with approval ticks and a house.AIPAGREEMENT IN PRINCIPLE
Limited Company Buy To Let

More landlords are considering whether to purchase property through a limited company.

We can compare limited company and personal buy-to-let mortgage options, although you should obtain independent tax and legal advice before deciding how to structure your purchase.

Low Deposit MortgagesA house with a pound coin and a stack of coins representing a low deposit mortgage.£
Buy To Let Remortgages

If your current mortgage deal is ending, we can compare remortgage options with other lenders alongside any product transfer offered by your existing lender.

Help Understanding AffordabilityA calculator beside a financial document with a profile, lines and a bar chart.£
Portfolio Landlord Mortgages

If you own several rental properties, lenders may assess your entire portfolio as well as the property being mortgaged.

We can help organise the required information and identify lenders whose criteria may suit your circumstances.

Protection AdviceA protective shield with a tick beside a family.
Raising Capital From a Rental Property

You may be able to release equity from an existing buy-to-let property for purposes such as buying another property, carrying out improvements or consolidating borrowing.

This will depend on the property value, rental income, mortgage balance and lender criteria.

How it Works

Let us help you get your home today.

Step 1
Book Your Consultation

We will discuss your deposit, income, existing properties, expected rent and investment plans.

Step 2
Understand Your Budget

We will estimate how much you may be able to borrow and explain the likely deposit and monthly mortgage costs.

Step 3
Assess Rental Income

We will check whether the expected rent is likely to meet lenders’ rental coverage requirements.

Step 4
Compare Options

We will compare suitable mortgage products, including the interest rate, arrangement fees, valuation costs and early repayment charges.

Step 5
Submit Your Application

Once you are ready to proceed, we will prepare and submit the mortgage application to the chosen lender.

Step 6
Mortgage Offer and Completion

Once the mortgage is approved, we will continue to support you while the legal work is completed.

How can we offer all of this for free?

Like all mortgage brokers, we’re paid by lenders when your mortgage completes.  The difference between us and other mortgage brokers is that we simply choose not to charge our customers a fee on top of this.

EXCELLENT
Google star 1Google star 2Google star 3Google star 4Google star 5
Based on 217 reviews
Posted on Google Google
Ethan Raoul profile picture
Ethan Raoul
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Lauren has been such a huge help to us as first time buyers. She guided us through the mortgage process and made everything feel much easier to understand and manage. When our first property didn’t work out, she helped us switch the mortgage to our new property and secured the original rate, which we were so grateful for. We really appreciate all her help and support throughout the process and would highly recommend her to anyone, especially other first-time buyers. Thank you, Lauren!
Posted on Google Google
Vanessa Lucena Hurla profile picture
Vanessa Lucena Hurla
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We had a fantastic experience working with Lauren at Mortgage Links throughout our mortgage application. She was professional, knowledgeable and incredibly helpful from start to finish, always keeping us updated and taking the time to answer our questions clearly. Lauren made the whole process feel much easier and less stressful, and we truly appreciated her support and guidance at every stage. We couldn’t recommend her highly enough and would happily work with her again in the future. Thank you so much for everything, Lauren!
Posted on Google Google
Nic B profile picture
Nic B
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We’ve been using Mortgage Links for years now and could not recommend enough. They prompt us when our deal is due to end, they are always very amenable when organising appointments, advice is always honest and ongoing communication is regular and plentiful. James is also very patient, relaxed and happy to explore options with us, which is really helpful when making big life decisions!
Posted on Google Google
Madalaine daisy Sole profile picture
Madalaine daisy Sole
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Our experience with mortgage links has been nothing but positive. Our correspondence has solely been with Lauren Conroy who has been extremely attentive with our situation and helping us the best she can. As first time buyers she has taken her time throughly explaining everything in detail, ensuring we understand all the information she has provided, yet doing this in a way that is digestible without making us feel overwhelmed with copious amounts of information. She has been completely transparent since the beginning and we honestly could not recommend her enough.
Posted on Google Google
Andy Green RHAA profile picture
Andy Green RHAA
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I can't recommend Kate highly enough. She sorted out a specialist mortgage when our chain collapsed allowing us to buy another property and keep our existing property for rental, and with immediate help 👍👍
Posted on Google Google
cassandra angelides profile picture
cassandra angelides
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
First time buyer, and very daunted to start the process, first initial meeting with James and I was instantly put at ease, I hadn’t a clue and he explained everything in simple terms and made a complicated journey easy. He has a nice laid back way about him, and in contrast when I contacted him even with a silly question he replied very fast. James is a super fast worker and had my mortgage sorted so much sooner than I anticipated. I will 100% be recommending him to family and friends. Thanks James
Posted on Google Google
Beth Ward profile picture
Beth Ward
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Absolutely amazing service. Kate made everything a breeze. As first time buyers, there were a lot of unknowns and questions we had before going into the process. Kate answered every question we had and put our minds at ease, not only through the mortgage process but throughout the full buying timeline. She was attentive, supportive and a great communicator. Thank you so so much!
Posted on Google Google
Mojola Coker profile picture
Mojola Coker
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Lauren helped me & my partner as a mortgage advisor for the purchase of our first home and she was honestly brilliant! She answered all our questions & guided us through the process seamlessly. She is extremely personable and is very knowledgeable. Would recommend her in a heart beat!
Posted on Google Google
Julia Nicoll profile picture
Julia Nicoll
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
So glad I have found a broker I can trust, highly recommend
Posted on Google Google
Emily Tattersall profile picture
Emily Tattersall
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Lauren from mortgage links has been our mortgage adviser for our current house purchase and is absolutely amazing. She talked us through all our options, found the best deal and when a better rate became available secured us that too! Nothing is too much and she works at the speed of light! Fantastic service and would recommend to anyone 😊

Ready to Discuss Your Buy To Let Plans?

Whether you are buying your first rental property, expanding your portfolio or reviewing an existing mortgage, we are here to help.

Book your free, no-obligation consultation and find out what buy to let mortgage options may be available.

Buy To Let Mortgage FAQs

Common Buy To Let Mortgage Questions

How much deposit do I need for a buy to let mortgage?

Many buy-to-let lenders require a deposit of at least 20% to 25% of the property value. A larger deposit may provide access to a wider range of lenders and potentially more competitive mortgage rates. The exact amount required will depend on the property, expected rent, your circumstances and the lender’s criteria.

How much can I borrow on a buy to let mortgage?

The amount you can borrow will often be based largely on the rent the property is expected to generate. The lender will check whether the rent covers the mortgage payment by a sufficient margin using its own stress-testing calculation. Some lenders will also take your personal income into account.

Can I get a buy to let mortgage as a first-time landlord?

Yes. A number of lenders consider applicants buying their first rental property. However, some lenders may require you to already own your own home, meet a minimum personal income requirement or have a larger deposit. We can identify lenders whose criteria are more suitable for first-time landlords.

Can a first-time buyer get a buy to let mortgage?

It may be possible, but the choice of lenders is usually more limited. Lenders may look closely at why you are buying the property, where you currently live and whether the proposed arrangement appears credible. Some lenders may also assess the application using both rental and residential affordability considerations.

What is rental stress testing?

Rental stress testing is the calculation lenders use to check whether the expected rental income is sufficient to support the mortgage. The lender may assess the rent against a higher notional interest rate rather than the actual rate you will initially pay. Each lender uses its own calculation, so your maximum borrowing can vary significantly.

Do I need a minimum income for a buy-to-let mortgage?

Some lenders require a minimum personal income, while others may be willing to consider the application primarily on the expected rental income. Your employment status, credit history and existing commitments may still be taken into account.

Are buy to let mortgage rates higher?

Buy-to-let mortgage rates and fees can be higher than those available on standard residential mortgages. The overall cost will depend on the deposit, property type, mortgage term, lender and whether you are applying personally or through a company. It is important to compare the full cost of the mortgage rather than focusing only on the headline rate.

What costs should I budget for?

In addition to your deposit, you may need to budget for: Property taxes applicable to the purchase, Solicitor and conveyancing fees, Mortgage lender product fees, Valuation or survey costs, Letting agent fees, Buildings and landlord insurance, Repairs and ongoing maintenance, Safety checks and compliance costs, Periods when the property may be empty and Accountant or tax adviser fees. You should obtain specialist tax advice about the costs and tax treatment associated with owning rental property.

Should I buy a rental property personally or through a limited company?

The most suitable ownership structure will depend on your tax position, future plans, borrowing requirements and how you intend to use the rental income. We can explain the mortgage options available under each structure, but you should obtain advice from a qualified accountant or tax adviser before making a decision.

Can I remortgage my buy-to-let property?

Yes. You may be able to remortgage to secure a new deal, change the mortgage term or release equity. Before recommending a remortgage, we will consider any early repayment charges, arrangement fees, legal costs and the product transfer options available from your current lender.

Can I release equity to buy another rental property?

Potentially, yes. If your property has increased in value or the mortgage balance has reduced, you may be able to release some of the available equity. The lender will consider the property value, expected rent, remaining equity and the reason for raising the funds. We will explain what type of credit search is likely to be completed before proceeding with an application.

Can I live in a property with a buy to let mortgage?

A standard buy-to-let mortgage is generally intended for a property that is rented to tenants and not occupied by you or your immediate family. Living in the property without the lender’s permission could breach the mortgage conditions. You should speak to your lender or mortgage adviser before changing how the property is occupied.

Can I rent a property to a family member?

Renting to a close family member may require a regulated buy-to-let mortgage rather than a standard buy-to-let product. The choice of lenders may be more limited, so it is important to explain the intended tenancy arrangement from the outset.

Can I use a buy to let mortgage for an HMO?

Potentially, although a standard buy-to-let mortgage may not be suitable for a house in multiple occupation. HMO lenders may have specific requirements around landlord experience, licensing, property size and the number of tenants. Specialist mortgage advice is recommended before making an offer.

Can I get a buy-to-let mortgage with bad credit?

Previous credit problems do not always prevent you from obtaining a buy-to-let mortgage. Your options will depend on the type of issue, the amount involved, when it occurred and whether it has now been resolved. Approaching the right lender is particularly important where there has been adverse credit.

Do I need landlord insurance?

Buildings insurance will normally be required by the mortgage lender. You may also wish to consider landlord insurance covering areas such as property damage, liability, loss of rent and legal expenses. The appropriate cover will depend on the property and tenancy arrangement.