First Time Buyer Mortgages

Buying Your First Home? We’ll Guide You Every Step of the Way.

Hassle Free
Mortgage Advice

Request A Free Video Call

Buying your first property is exciting, but it can also feel overwhelming. From working out how much you can borrow to understanding deposits, mortgage rates and the buying process, there’s a lot to take in.

At Mortgage Links, we make buying your first home as straightforward as possible. We’ll explain everything in plain English, compare mortgages from across the market, and support you from your first enquiry right through to getting your keys.

Book your free consultation today and let’s get you moving.
We have access to 90+ Lenders

What We do

Why Choose Mortgage Links?

Buying your first home isn’t just about finding a mortgage—it’s about having someone in your corner.

We will help you:

  • Understand exactly how much you can borrow.
  • Explain every cost involved before you commit.
  • Compare mortgages from a wide range of UK lenders.
  • Help improve your chances of being accepted.
  • Liaise with lenders, estate agents and solicitors.
  • Keep you updated throughout the entire process.
  • Arrange any protection you may need once you’re a homeowner.
 

Whether you’re buying on your own, as a couple or with family support, we’re here to make the process simple.
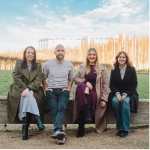
Mortgage Links Team Sheffield
Established

2022

What Can We Help With?

Here to help you through every stage of your mortgage journey

First-time buyer mortgage iconA house, keys and approved mortgage document representing a first-time buyer mortgage.FIRST-TIMEBUYERMORTGAGE
First Time Buyer Mortgages

We'll find a mortgage that's right for your circumstances, not just the lowest interest rate.

Agreement in Principle mortgage iconA clipboard marked AIP Agreement in Principle with approval ticks and a house.AIPAGREEMENT IN PRINCIPLE
Agreement in Principle

Often needed before viewing or making an offer, we'll arrange your Agreement in Principle quickly.

Low Deposit MortgagesA house with a pound coin and a stack of coins representing a low deposit mortgage.£
Low Deposit Mortgages

Have a 5% or 10% deposit or less? We'll explain which lenders are available and what options may suit you.

Help Understanding AffordabilityA calculator beside a financial document with a profile, lines and a bar chart.£
Help Understanding Affordability

We'll explain how lenders assess your income, spending and credit history so you know where you stand.

Protection AdviceA protective shield with a tick beside a family.
Protection Advice

We'll discuss options such as life insurance, income protection and critical illness cover to help protect you and your family.

How it Works

Let us help you get your home today.

Step 1
Book Your Consultation

We'll discuss your income, deposit, credit history and future plans.

Step 2
Calculate Your Budget

We'll tell you how much you may be able to borrow and explain your monthly repayments.

Step 3
Obtain an Agreement in Principle

This gives you confidence when viewing properties and making offers.

Step 4
Find Your Home

Once you've found the right property, we'll submit your full mortgage application.

Step 5
Mortgage Offer

We'll keep you informed throughout the lender's assessment and answer any questions along the way.

Step 6
Exchange & Completion

Once everything is complete, you'll collect the keys to your new home.

How can we offer all of this for free?

Like all mortgage brokers, we’re paid by lenders when your mortgage completes.  The difference between us and other mortgage brokers is that we simply choose not to charge our customers a fee on top of this.

EXCELLENT
Google star 1Google star 2Google star 3Google star 4Google star 5
Based on 217 reviews
Posted on Google Google
Ethan Raoul profile picture
Ethan Raoul
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Lauren has been such a huge help to us as first time buyers. She guided us through the mortgage process and made everything feel much easier to understand and manage. When our first property didn’t work out, she helped us switch the mortgage to our new property and secured the original rate, which we were so grateful for. We really appreciate all her help and support throughout the process and would highly recommend her to anyone, especially other first-time buyers. Thank you, Lauren!
Posted on Google Google
Vanessa Lucena Hurla profile picture
Vanessa Lucena Hurla
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We had a fantastic experience working with Lauren at Mortgage Links throughout our mortgage application. She was professional, knowledgeable and incredibly helpful from start to finish, always keeping us updated and taking the time to answer our questions clearly. Lauren made the whole process feel much easier and less stressful, and we truly appreciated her support and guidance at every stage. We couldn’t recommend her highly enough and would happily work with her again in the future. Thank you so much for everything, Lauren!
Posted on Google Google
Nic B profile picture
Nic B
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We’ve been using Mortgage Links for years now and could not recommend enough. They prompt us when our deal is due to end, they are always very amenable when organising appointments, advice is always honest and ongoing communication is regular and plentiful. James is also very patient, relaxed and happy to explore options with us, which is really helpful when making big life decisions!
Posted on Google Google
Madalaine daisy Sole profile picture
Madalaine daisy Sole
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Our experience with mortgage links has been nothing but positive. Our correspondence has solely been with Lauren Conroy who has been extremely attentive with our situation and helping us the best she can. As first time buyers she has taken her time throughly explaining everything in detail, ensuring we understand all the information she has provided, yet doing this in a way that is digestible without making us feel overwhelmed with copious amounts of information. She has been completely transparent since the beginning and we honestly could not recommend her enough.
Posted on Google Google
Andy Green RHAA profile picture
Andy Green RHAA
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I can't recommend Kate highly enough. She sorted out a specialist mortgage when our chain collapsed allowing us to buy another property and keep our existing property for rental, and with immediate help 👍👍
Posted on Google Google
cassandra angelides profile picture
cassandra angelides
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
First time buyer, and very daunted to start the process, first initial meeting with James and I was instantly put at ease, I hadn’t a clue and he explained everything in simple terms and made a complicated journey easy. He has a nice laid back way about him, and in contrast when I contacted him even with a silly question he replied very fast. James is a super fast worker and had my mortgage sorted so much sooner than I anticipated. I will 100% be recommending him to family and friends. Thanks James
Posted on Google Google
Beth Ward profile picture
Beth Ward
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Absolutely amazing service. Kate made everything a breeze. As first time buyers, there were a lot of unknowns and questions we had before going into the process. Kate answered every question we had and put our minds at ease, not only through the mortgage process but throughout the full buying timeline. She was attentive, supportive and a great communicator. Thank you so so much!
Posted on Google Google
Mojola Coker profile picture
Mojola Coker
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Lauren helped me & my partner as a mortgage advisor for the purchase of our first home and she was honestly brilliant! She answered all our questions & guided us through the process seamlessly. She is extremely personable and is very knowledgeable. Would recommend her in a heart beat!
Posted on Google Google
Julia Nicoll profile picture
Julia Nicoll
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
So glad I have found a broker I can trust, highly recommend
Posted on Google Google
Emily Tattersall profile picture
Emily Tattersall
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Lauren from mortgage links has been our mortgage adviser for our current house purchase and is absolutely amazing. She talked us through all our options, found the best deal and when a better rate became available secured us that too! Nothing is too much and she works at the speed of light! Fantastic service and would recommend to anyone 😊

Ready to Buy Your First Home?

Whether you’re just starting to save or you’ve already found your dream property, we’d love to help.

Book your free, no-obligation consultation today and find out how much you could borrow.

First Time Buyer Mortgage FAQs

Common Questions From First Time Buyers

How much deposit do I need as a first time buyer?

Some mortgage lenders may accept a deposit of 2-5% of the property’s purchase price, although putting down 10% or more will usually give you access to a wider choice of mortgage products and potentially lower interest rates. The deposit required will depend on the property, your income, your credit history and the lender’s individual criteria.

Can I get a first time buyer mortgage with a 5% deposit?

Yes, 95% loan-to-value mortgages are available from a number of lenders, subject to affordability checks and lending criteria. A 5% deposit can help you buy sooner, but the interest rates may be higher than those available with a larger deposit. We can compare the available options and explain the difference in monthly and overall costs.

Do I need an Agreement in Principle before viewing houses?

You do not always need an Agreement in Principle before arranging a viewing, but some estate agents may ask for one before accepting an offer or confirming that you are in a position to proceed. Obtaining one early can also help you avoid looking at properties outside your realistic budget.

Can I get a mortgage with bad credit as a first-time buyer?

Having previous credit problems does not automatically prevent you from getting a mortgage. Your options will depend on the type of credit issue, the amount involved, when it occurred and whether it has now been resolved. Some lenders are more flexible than others, so it is important to approach the right lender rather than making multiple applications.

Can I use a Lifetime ISA towards my first home?

You may be able to use savings held within a Lifetime ISA towards an eligible first-home purchase, provided the relevant rules and withdrawal conditions are met. You should check the current Lifetime ISA requirements and give your solicitor enough time to request the funds before completion.

Can I get a mortgage during a probationary period?

Potentially, yes. Some lenders will consider applicants who have recently started a job or are still within their probationary period. The lender may ask for an employment contract, payslips or confirmation of your start date and salary. Your previous employment history and the nature of your new role may also be considered.

Can I buy a house with someone who is not my partner?

Yes. You can apply for a mortgage with a friend, sibling or family member. You should take legal advice about how the property will be owned, how the deposit is recorded and what would happen if one person wanted to sell or move out in the future.

How long does a first time buyer mortgage application take?

A straightforward mortgage application may receive an offer within a few weeks, but timescales vary between lenders and individual cases. The full home-buying process usually takes longer because it also includes the survey, legal work, property searches, enquiries and communication between everyone in the chain.

Should I choose a fixed-rate or variable-rate mortgage?

A fixed-rate mortgage provides certainty because the interest rate and monthly payment are normally fixed for an agreed period. A variable or tracker mortgage may rise or fall depending on the product terms and changes in interest rates. The most suitable option will depend on your budget, plans and attitude towards changes in monthly payments.

Can I make overpayments on my first mortgage?

Many mortgages allow you to make overpayments, although limits and early repayment charges may apply. Overpaying can reduce the mortgage balance, shorten the term and lower the amount of interest paid. You should always check the conditions of your mortgage before making a large overpayment.

What is an Agreement in Principle?

An Agreement in Principle, sometimes called a Decision in Principle or Mortgage in Principle, is an indication of how much a lender may be prepared to lend based on the information provided. It is not a formal mortgage offer, but it can help you understand your budget and demonstrate to estate agents that you are able to proceed with a purchase.

How much can I borrow for my first mortgage?

The amount you can borrow will depend on your income, regular financial commitments, credit history, deposit and the mortgage term. Lenders assess affordability differently, so the amount offered by one lender may be very different from another. We can calculate a personalised borrowing estimate and identify lenders that may be suitable for your circumstances.

Does an Agreement in Principle affect my credit score?

This depends on the lender. Some lenders use a soft credit search, which is not normally visible to other lenders, while others may carry out a hard credit search. We will explain what type of credit search is likely to be completed before proceeding with an application.

Can my family help with my first time buyer deposit?

Yes. Many lenders accept deposits gifted by parents or other close family members. The person providing the deposit will normally need to confirm that the money is a genuine gift, that it does not need to be repaid and that they will not own an interest in the property. Evidence showing the source of the funds may also be required.

Can I get a mortgage if I am self-employed?

Yes. First-time buyers who are self-employed can obtain a mortgage, although lenders may assess income in different ways. Depending on how your business is structured, a lender may consider your salary, dividends, share of net profit, latest accounts or tax calculations. The length of time you have been trading can also affect your options.

Can overtime, bonuses and commission count towards my mortgage?

Many lenders will consider overtime, bonuses and commission, although they may not use all of the income. They will usually want to see evidence that the additional income is regular and sustainable. This may include several months of payslips, a P60 or confirmation from your employer.

What costs do first time buyers need to budget for?

In addition to your deposit, you may need to budget for: Solicitor and conveyancing fees, Survey or valuation costs, Mortgage product fees, Removal costs, Buildings insurance, Initial repairs and furniture and stamp duty.

Do first-time buyers pay Stamp Duty?

First-time buyers may qualify for Stamp Duty Land Tax relief when purchasing an eligible property in England or Northern Ireland. The rules, property-price limits and tax rates can change, so you should check the position that applies at the time of your purchase. Different property taxes apply in Scotland and Wales.

What documents will I need for a first time buyer mortgage?

The documents required will depend on your circumstances, but commonly include: Proof of identity, Proof of address, Recent bank statements, Payslips or evidence of self-employed income, Evidence of your deposit, Details of loans, credit cards and other commitments, Proof of any gifted deposit and Details of the property you are buying.

Do I need life insurance when buying my first home?

Life insurance is not usually a legal requirement for obtaining a mortgage, although a lender will normally require suitable buildings insurance. It is worth considering how the mortgage would be paid if you died, became seriously ill or were unable to work. We can discuss life insurance, critical illness cover and income protection alongside your mortgage.